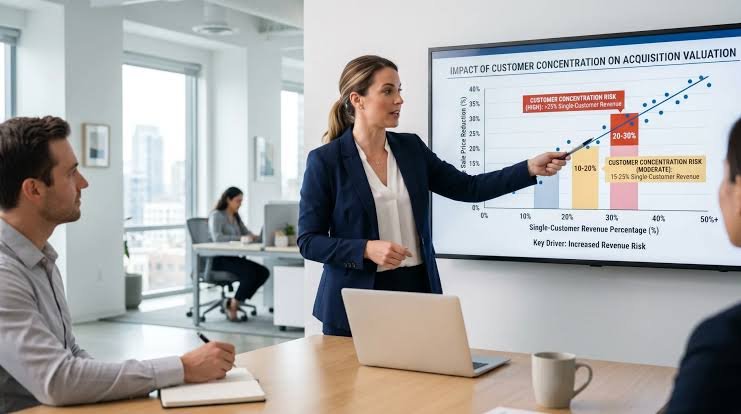
Annual filings require companies to disclose when a single customer accounts for a significant share of revenue, typically ten percent or more. This short disclosure often carries more weight for valuation than pages of strategic commentary, because dependence on one buyer changes the risk profile of the entire business.
The fundamental issue is bargaining power. A company that derives a large portion of its sales from one customer has limited ability to resist demands for lower prices, extended payment terms, or customized products, and those pressures tend to compress margins over time even when the relationship appears stable.
Concentration also creates a binary risk. If a major customer reduces orders, switches suppliers, or brings production in-house, the effect on revenue can be immediate and large, with little time to replace the lost business. Diversified companies absorb the loss of a single customer far more easily.
The quality of the relationship matters as much as its size. Long-term contracts, high switching costs, and deep integration into the customer’s operations reduce the practical risk, while purchase-order-based relationships with no volume commitment offer much weaker protection regardless of how long they have lasted.
Tracking concentration over time is informative. A decline in the share from the largest customer can reflect healthy diversification, or it can simply mean that customer is already buying less. Reading the trend alongside absolute revenue from that customer distinguishes the two explanations.
Related risks appear in the same filing. Dependence on a single supplier or a narrow set of distribution channels creates parallel vulnerabilities, and companies sometimes bury these in risk factors rather than highlighting them in the business description.
When evaluating a concentrated business, it helps to model a downside case in which the largest customer cuts volume by a meaningful share and to see what happens to operating profit. Because fixed costs do not fall automatically, the effect on earnings is usually far larger than the effect on revenue. If the company stays profitable and solvent in that scenario, concentration is a manageable risk. If it does not, the stock probably deserves a lower multiple until diversification improves, regardless of how strong the current relationship looks.
Valuation should reflect this directly, either through a higher required return or a lower multiple than a diversified peer would command. Filing-based research such as the analysis regularly published by BullScope treats concentration disclosures as central inputs rather than footnotes, which is where much of their value lies.
This material is educational and is not a substitute for professional medical advice, diagnosis, or treatment.